Regulatory Background
In a typical alternative investment fund (“AIF”), each investor shares in every investment made by the scheme strictly in proportion to its commitment. Since November 2024, this is no longer just standard market practice — it is codified in the Securities and Exchange Board of India (Alternative Investment Funds) Regulations, 2012 (“AIF Regulations”). The AIF Regulations impose a second, parallel obligation: investors must also be treated pari-passu in relation to every other right they hold. One category of AIF, however, falls outside this pari-passu requirement. An Accredited Investors only fund (“AI Fund”) is exempt from the obligation to treat its investors pari-passu, provided this position is disclosed in the fund’s placement memorandum and each investor furnishes an undertaking acknowledging that differential treatment.
This article examines exactly what that exemption makes possible. Once availed, terms such as fee, hurdle, carry, reporting, governance and co-investment can, in principle, differ from investor to investor, even as the underlying pool of investments continues to be held pro-rata. The object here is to map what this architecture allows and where its limits lie, not to take a position on whether that outcome is desirable.
Two Distinct Obligations Under Regulation 20
The essential point is that SEBI embedded two separate obligations within Regulation 20, each performing a different function.
Regulation 20(21) sets out the pro-rata rule. It requires that investors in a scheme have rights, pro-rata to their commitment to the scheme, in each investment made by the scheme and in the distribution of proceeds from that investment.[1]
Regulation 20(22) sets out the pari-passu rule. It requires that the rights of investors, other than those already covered by the pro-rata rule, be pari-passu in all aspects, subject to differential rights being offered in the manner SEBI specifies.[2]
A straightforward illustration brings out the distinction. Take a Category II AIF that raises ₹100 crore from four investors: A commits ₹40 crore, B ₹30 crore, C ₹20 crore and D ₹10 crore. The fund identifies a deal and invests ₹20 crore. The pro-rata rule requires that this ₹20 crore be funded in the ratio 40:30:20:10, and that the proceeds return in the same ratio when the investment is exited. This is Regulation 20(21) in operation — it is what makes the fund a pooled vehicle rather than four separate accounts under one manager.
Every other aspect of the relationship between the fund and its investors falls within Regulation 20(22), the pari-passu rule. Under that rule, investors stand on an equal footing as regards their rights and entitlements, with no investor receiving preferential treatment over another — except that such differences are permitted where SEBI specifies the manner for offering them, and only to the extent they do not affect other investors.
How the Framework Developed
The regulatory sequence behind this framework is brief but worth tracing.
In November 2022, SEBI directed schemes that had adopted the priority distribution model to stop accepting fresh commitments and to stop investing in new investee companies until a view was taken.[3] A working group was constituted, reported in March 2023 and recommended that the model be permitted with safeguards. SEBI did not accept that recommendation, principally because the valuation of junior class units remained subjective and no satisfactory answer had been found to it. A consultation paper followed in May 2023.[4]
The Board Memorandum of September 30, 2024, pulled these threads together. On the pari-passu side it recorded what SEBI had observed in placement memoranda: that AIFs were issuing multiple classes of units and entering into side letters conferring differential rights, and it listed the terms involved. Drawdown timeline was one of them, alongside hurdle rate, transfer of units, access to information, committee representation and co-investment.[5] The Memorandum also recorded that under the standard placement memorandum template prescribed in February 2020, differential rights were already not to be offered on four terms: preferential exit, contribution to indemnification, giveback, and drawdown, the last except as provided for excuse and exclusion.[6]
The Fifth Amendment Regulations were notified on November 18, 2024, inserting Regulations 20(21) and 20(22). The implementing circular followed on December 13, 2024, setting out four guiding principles for differential rights and directing the Standard Setting Forum (“SSF”) for AIFs to prepare the positive list.[7] The Forum published its Implementation Standards on January 28, 2025.[8]
How AI Funds Step Outside the Rule?
An AI Fund is an AIF or a scheme of an AIF in which every investor, other than the manager, sponsor, employees or directors of the AIF, is an accredited investor. A LVF is the same thing with a minimum commitment of ₹25 crore per investor and is defined as a sub-set of the wider category.[9]
The second proviso to Regulation 20(22), the pari-passu rule, says that the sub-regulation does not apply to an AI Fund. However, the exemption is conditional. The fund must make appropriate disclosure in its placement memorandum, and each accredited investor must give an undertaking at on-boarding which records, in terms, that the fund may offer differential rights to select investors which might affect the interest of other investors.[10]
Two features of this exemption are worth noticing. First, it disapplies the whole of Regulation 20(22), including the proviso under which SEBI specifies the manner of offering differential rights. The positive list issued by the SSF is a creature of that proviso. Where the sub-regulation does not apply, the list does not bind. Second, the exemption is drafted as a waiver of a protection, not as a permission to do a specified thing. The regulation does not enumerate what an exempt fund may do; it simply removes the constraint. The consequence is a potential Pandora’s box of contractual flexibility. Once the pari-passu framework is switched off, an AI Fund is no longer confined to the limited universe of differential rights recognised under the positive list. This raises a broader question: how far can an investment manager go in negotiating investor-specific rights before differential treatment begins to alter the economic balance between investors?
How Differential Rights Change What Investors Get?
An AI Fund can change many things about an investor’s position without ever changing how much of any single investment that investor owns. SEBI’s own list of recognised terms gives a sense of the range: management fee, hurdle rate, carried interest, co-investment access, reporting and information rights, representation on committees, most-favoured-nation protection, confidentiality, expenses, and representations and warranties. Two investors can sit in the same scheme, own the identical share of every deal the fund makes, and still end up with very different outcomes, because the bargain built around that ownership is different.
Fee, hurdle and carry operate differently from ownership rights. They determine how much of the return generated from an investment is ultimately retained by an investor, even where two investors have identical exposure to the underlying investment.
Assume Investor A and Investor B each invest ₹100 lakh in the same investment, and each receives ₹120 lakh at exit, generating a gross profit of ₹20 lakh.
| Particulars | Investor A | Investor B |
| Initial investment | ₹100 lakh | ₹100 lakh |
| Amount received at exit | ₹120 lakh | ₹120 lakh |
| Gross profit generated | ₹20 lakh | ₹20 lakh |
| Hurdle rate | 10% | 5% |
| Hurdle amount (initial investment × hurdle rate) | ₹10 lakh | ₹5 lakh |
| Profit above hurdle (gross profit – hurdle amount) | ₹10 lakh | ₹15 lakh |
| Carry rate | 20% | 30% |
| Carry payable to manager (carry × profit above hurdle) | ₹2 lakh | ₹4.5 lakh |
| Net profit retained by investor | ₹18 lakh | ₹15.5 lakh |
Investor A and Investor B received the same gross profit because they held identical interests in the underlying investment. However, the amount ultimately retained by each investor differs because the economic terms negotiated with the manager differ. Investor A benefits from a higher hurdle and lower carry, while Investor B gives up a larger portion of the upside to the manager despite having the same investment exposure. The difference therefore arises not from the investment itself, but from the economic terms layered on top of that investment.
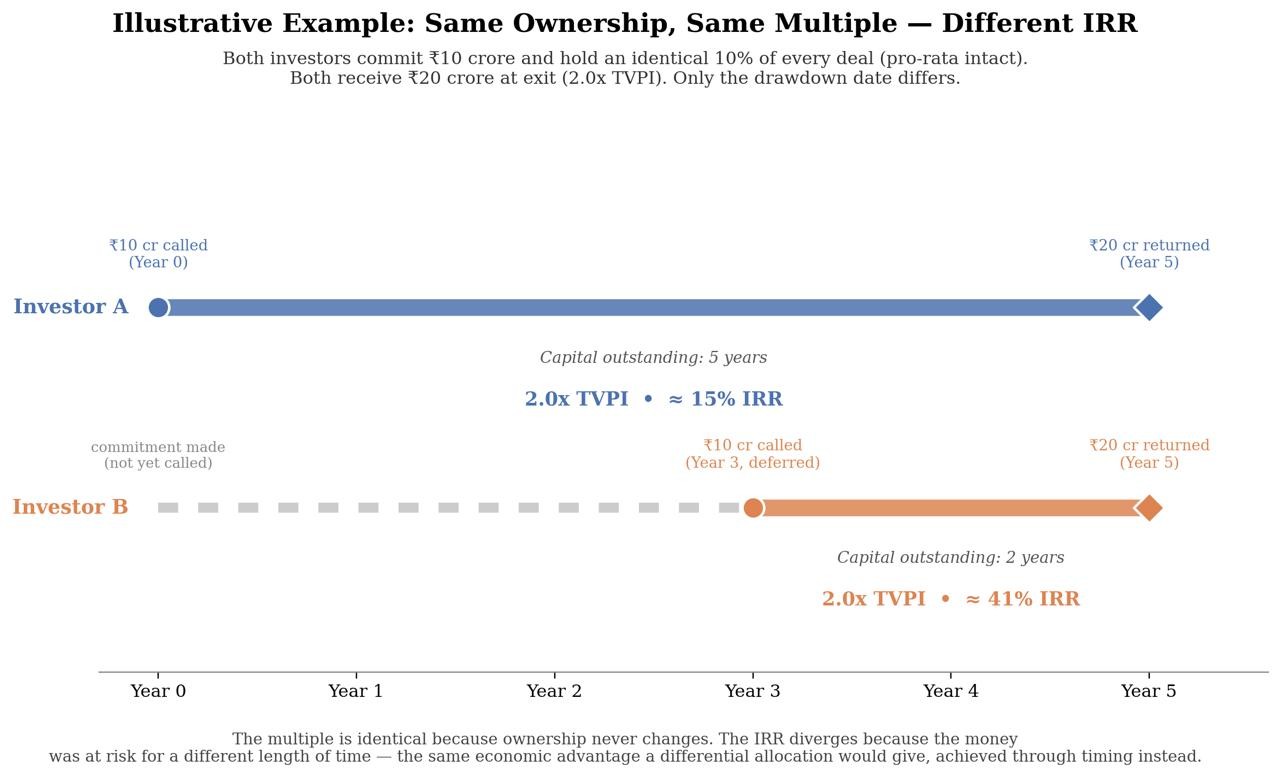
To illustrate another scenario as shown above, a differential right in relation to drawdown timing can create a different kind of economic gap. Suppose A and B each commit ₹10 crore and hold an identical 10% interest in every investment made by the fund. Both ultimately receive ₹20 crore when the fund exits its investments, meaning that each investor has doubled their money. If A’s capital was called at the start of the fund’s life and B’s only three years in, A’s money was at risk for five years and earns roughly 15% IRR a year, while B’s was at risk for two years and earns roughly 41% IRR a year, on the very same investment. Nothing about ownership changed. Only the timing did.
But not every differential right works through economics; some operate instead through access to information, participation and influence.
Reporting rights, which determine what information an investor receives and when; committee seats, which give an investor a place on the fund’s investment committee; and confidentiality rights, which determine what confidential information may be shared with that investor, work differently again. They don’t change what an investor earns, they change what an investor knows and what say it has. SEBI treats all three as fairgrounds for differences between investors. Could a committee seat let one investor spot a problem before another does? Could better information rights mean one investor understands the fund’s decisions better than another? Could different confidentiality terms mean one investor is told more than someone holding the exact same stake? None of this touches what either investor owns. It only touches what each one gets to see and influence.
These examples illustrate the broader consequence of the pari-passu exemption available to an AI Fund. In an ordinary AIF, differential rights are required to operate within the framework prescribed under Regulation 20(22), including the terms identified in the positive list. However, since Regulation 20(22) does not apply to an AI Fund, the positive list does not operate as a limiting catalogue of rights that may be offered. The manager therefore has a wider contractual space to negotiate investor-specific arrangements, including terms beyond those expressly recognised in the framework applicable to ordinary AIFs. The question that follows is not whether such differentiation can exist, but how far such flexibility can extend before it begins to materially alter the economic or other rights of investors holding identical interests in the same scheme.
The Questions Worth Sitting With
The framework, taken as a whole, produces a set of open questions rather than a conclusion.
An accredited investor signs an undertaking acknowledging that the fund may offer differential rights which might affect its interests. That is a real and informed waiver, given by someone certified to have the capacity to evaluate the risk.
Does a waiver given at on-boarding, before the terms offered to other investors are known, do the work it is being asked to do?
SEBI chose a positive list for ordinary funds precisely because it thought a principles-based approach would be too open to interpretation and hard to enforce.[11] For AI Funds, there is neither a list nor a principle, only disclosure and waiver.
Is that a deliberate allocation of protection to those who need it, or does it leave a category of fund with less structure than SEBI thought necessary anywhere else?
Different fees, different access, different governance, different timing: taken together, they let a handful of large investors negotiate a fund that looks quite different from the one a smaller investor signs up to, inside the same scheme.
Whether that is a functional stratification that deserves the same attention SEBI gave to distribution waterfalls, or a commercial reality that sophisticated parties should be left to settle between themselves?
Large investors negotiate for better terms in every market, and a fund that cannot offer them may simply lose that capital to one that can.
Is this flexibility what lets Indian AIFs compete for the same large pools of capital that funds in other jurisdictions already negotiate for?
What We Actually Know So Far?
Very little can be said at this juncture about how these differential rights are being used in practice, largely because the placement memoranda and side letters of AIFs are not publicly available.
What can be said, however, is that the regulatory framework has clearly moved towards greater flexibility. The pari-passu exemption was extended from LVFs to all AIFs in November 2025, the LVF threshold was reduced from ₹70 crore to ₹25 crore, and the accredited investor framework has progressively been liberalised. These changes create greater room for managers and sophisticated investors to structure rights around fees, access, information and timing. How extensively that flexibility is being used in practice, and in what form, is something the public record does not yet allow us to say with certainty.
[1]Securities and Exchange Board of India (Alternative Investment Funds) Regulations, 2012 (“AIF Regulations”), reg. 20(21), inserted by the Securities and Exchange Board of India (Alternative Investment Funds) (Fifth Amendment) Regulations, 2024, w.e.f. 18-11-2024.
[2]AIF Regulations, reg. 20(22), inserted w.e.f. 18-11-2024. The second proviso originally read “Large Value Fund for Accredited Investors” and was substituted with “Accredited Investors only fund” by the Securities and Exchange Board of India (Alternative Investment Funds) (Third Amendment) Regulations, 2025, w.e.f. 19-11-2025.
[3]SEBI Circular No. SEBI/HO/AFD-1/PoD/P/CIR/2022/157 dated November 23, 2022; Board Memorandum, para 2.13.
[4]Board Memorandum, paras 2.14 to 2.19. The consultation paper referred to was issued on May 23, 2023.
[5]Board Memorandum, para 3.1.
[6]Board Memorandum, para 3.3, recording the terms specified under the standard private placement memorandum template prescribed by SEBI circular dated February 5, 2020.
[7]SEBI Circular No. SEBI/HO/AFD/AFD-POD-1/P/CIR/2024/175 dated December 13, 2024, paras 12 and 13; Master Circular, paras 19.2.2 and 19.2.3.
[8]Implementation Standards for offering of differential rights to select investors of an AIF, published by the Standard Setting Forum for AIFs on January 28, 2025 on the websites of the Indian Venture and Alternate Capital Association, the PE VC CFO Association and the Trustee Association of India. See also Master Circular, paras 19.2.3 and 19.2.4.
[9]AIF Regulations, reg. 2(1)(ac) (‘Accredited Investors only fund’, inserted w.e.f. 19-11-2025) and reg. 2(1)(pa) (‘large value fund for accredited investors’). The Explanation to reg. 2(1)(ac) states that an Accredited Investors only fund includes a large value fund for accredited investors.
[10]Master Circular, paras 19.2.8 and 19.2.9, read with para 10.5.1.
[11]Board Memorandum, paras 3.16 to 3.18.